Contact Sales (402) 933-4864


Written by: Erin Wright
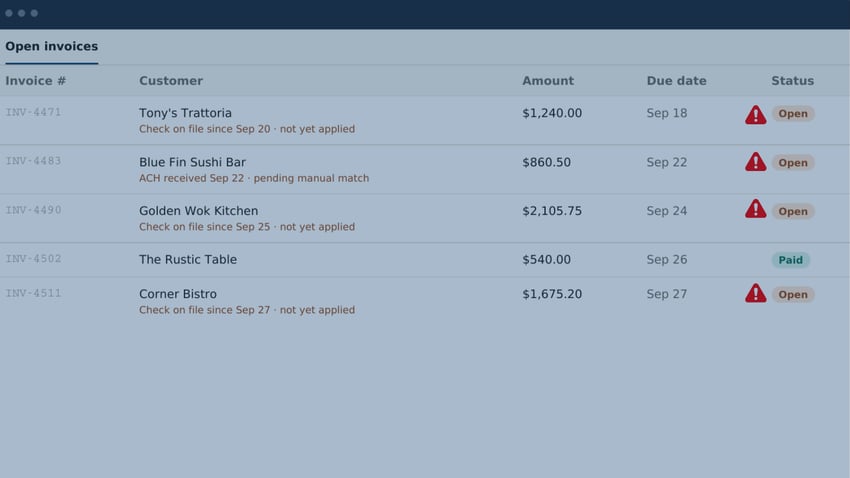
If your Days Sales Outstanding (DSO) keeps creeping up, the fastest fix usually isn't chasing customers harder. It's fixing how your team turns incoming payments into applied cash. In most B2B finance operations, DSO climbs not because customers pay late, but because remittance data is scattered across emails, PDFs, and paper checks, and nobody can match it to the right invoice fast enough. Close that gap and DSO often drops without a single collections call.
That distinction matters, because it changes where you spend your time and budget. Tightening credit terms won't help if your real problem is a backlog of unapplied cash. This blog walks through why DSO rises, how to diagnose the actual cause in your operations, and what finance teams are doing to reduce DSO.
Days Sales Outstanding measures the average number of days it takes to collect payment after a sale on credit. The formula is straightforward: divide your average accounts receivable balance by total credit sales for a period, then multiply by the number of days in that period.
There is no single "good" DSO number. It depends heavily on your industry and your standard payment terms. A useful rule of thumb: healthy DSO typically runs between 1.0 and 1.5 times your stated terms. If you invoice on Net 30 and your DSO sits at 35 to 40 days, that's reasonable. If it's pushing 60, something in your process needs attention.
For context, the Credit Research Foundation's quarterly DSO benchmarking survey has recently put the broad market median DSO in the low 40-day range, while industry medians can range from around 15 days in fast-moving retail categories to 80 or 90 days in construction and other project-billed sectors. The variation comes down to contract structure, payer mix, and how often invoices get disputed, not just how diligently a company collects.
Observation: Companies often benchmark against an industry average and conclude they're fine, when the more useful comparison is against their own DSO Efficiency Ratio, meaning actual DSO divided by stated terms. A company at "average" DSO for its industry can still be running a serious cash gap if its terms are shorter than that average assumes.
It's tempting to blame DSO increases on customers stretching payment terms. Sometimes that's true. But in most operations we see, the bigger driver is what happens after the payment has already arrived.
Here's the sequence that quietly inflates DSO in a lot of finance departments:
Industry research backs this up. PYMNTS Intelligence's "From Friction to Flow: AR Automation in 2025" report found that 83% of firms have yet to fully automate their AR operations. Straight-through processing rates, meaning the share of payments matched to invoices without any manual touch, typically run between 40% and 60% for teams still working from paper and email remittance, according to benchmarking data from the Institute of Finance & Management (IOFM). Well-configured automated matching, by contrast, routinely reaches 95% to 99%.
Observation: The gap between those two numbers is your real DSO opportunity. If your STP rate is 45%, more than half of every payment batch requires a human to manually decide what it covers before that cash counts as collected. That delay shows up in your DSO calculation exactly the same way a late-paying customer does, even though the money already landed in your account.
A rising DSO isn't just an accounting curiosity. It has direct consequences:
Customer scenario: A top-ten U.S. foodservice distributor's check payments and remittance details were coming in through disconnected channels, and the company's field sales representatives were often the ones physically collecting checks from customers, then manually routing them back to the office for processing and posting. The company centralized that process using FTNI's ETran platform, adding remote deposit capture so checks could be scanned and processed the moment they were received, and later rolling out a mobile payment solution so more than 300 field reps could accept and deposit payments on the spot instead of transporting them back to a branch. According to the distributor's Enterprise Credit Manager, "We no longer have to manually transport check payments, resulting in significant security and efficiency gains, and increased cash flow for our business. Now deposits can be made the same day payments are received. Our average DSO has decreased significantly in mere months." The DSO improvement here didn't come from a harder collections push. It came from closing the gap between when a customer paid and when that payment was applied.
Before choosing a fix, run this audit. It tells you exactly where your DSO is coming from.
Step 1: Calculate your DSO Efficiency Ratio
Divide your actual DSO by your average stated payment terms. A ratio between 1.0 and 1.15 is strong. Above 1.5 signals a real cash flow problem that will compound if left alone.
Step 2: Measure your straight-through processing rate
What percentage of incoming payments get matched to the correct invoice without anyone touching them? This single number tells you whether your issue is upstream (data capture) or downstream (actual collections).
Step 3: Categorize your remittance sources
List every format remittance data arrives in: Email attachments, paper check stubs, customer portals, PDFs. The more formats you're manually reconciling, the more your STP rate will suffer.
Step 4: Quantify your unapplied cash balance
Look at how much cash is sitting unmatched at any given time, and how long it typically stays there. This is often the clearest, most underused DSO indicator in a finance department.
Step 5: Separate true late payers from processing delays
Once you've isolated how much of your AR aging is caused by matching delays versus actual slow-paying customers, you know which problem to solve first, and whether that means a technology fix, a credit policy fix, or both.
Automate remittance capture across every format
The biggest lever most companies aren't pulling is capturing remittance data automatically regardless of how it arrives, whether that's an emailed PDF, a lockbox scan, or a portal submission. Structuring that data the moment it's received is what makes automated matching possible in the first place.
Move toward multi-format, rules-based matching
Modern matching engines apply payments using a hierarchy of rules (invoice number, amount, customer ID, partial payment logic) and only route genuine exceptions to a person.
Build a real exception management workflow
Automation should not mean "hope everything matches." Design a queue where unmatched payments are routed to the right person with context already attached, so exceptions get resolved in minutes rather than days.
Integrate directly with your ERP
Manual re-keying between a payment system and your general ledger is one of the most common places DSO gains quietly get lost. A direct integration keeps your aging report and your cash position accurate in real time.
Once a finance team has identified that it's not customer behavior that is the main driver of a high DSO, the fix is usually a platform purpose-built for their problem rather than a patchwork of manual workarounds.
This is the specific gap FTNI's ETran platform is built to close. ETran captures remittance data across multiple formats, applies rules-based matching to post payments automatically, and integrates directly with your ERP so your aging report reflects in real-time. The use of AR automation platforms delivers many benefits, perhaps none more important than helping businesses achieve straight-through processing and the efficiencies and cost savings that come with it. For finance teams that have run the diagnostic above and found their bottleneck sitting in cash application rather than collections, that's the layer worth automating first.
Most finance teams see measurable movement in their straight-through processing rate within the first billing cycle after implementation, since that metric reflects the technology directly. DSO itself typically takes one to two full collection cycles to show a clear trend, because it's a trailing average that includes receivables opened before the change. PYMNTS research has found that organizations with AR automation covering more than half of their operations saw DSO reductions of roughly 32%, equivalent to about 19 fewer days, though results vary based on starting STP rate and customer payment mix.
What is a good DSO for a B2B company?
It depends on your payment terms and industry. A commonly used benchmark is 1.0 to 1.5 times your stated terms. On Net 30, a DSO of 30 to 45 is generally healthy; anything meaningfully above that warrants investigation.
Does reducing DSO always require better collections?
No. In many operations, the fastest DSO improvement comes from automating cash application and remittance matching rather than changing how collections teams follow up with customers.
What is unapplied cash, and why does it matter for DSO?
Unapplied cash is money your company has received but hasn't yet matched to a specific invoice. Until it's applied, the related invoice still shows as outstanding, which inflates your DSO even though the customer has already paid.
How is DSO different from a straight-through processing (STP) rate?
DSO measures how long it takes to collect payment overall. STP rate measures what percentage of those payments get matched to invoices automatically, without manual intervention. A low STP rate is one of the most common hidden causes of a high DSO.
Can AR automation help with international or cross-border receivables?
Yes. Automated remittance capture and matching are especially valuable for global receivables, where payment formats, currencies, and banking rails vary by country and manual reconciliation becomes even more time-consuming.
How do I know if my DSO problem is a data problem or a customer problem?
Run the audit outlined above: measure your STP rate and unapplied cash balance. If a meaningful share of payments sit unmatched for days before they're applied, you're looking at a processing bottleneck rather than a customer payment behavior problem.
____________________________
A high DSO is frustrating because it feels like a customer problem you can't fully control. In practice, a large share of the DSO gap in most finance operations comes from something you can control: how fast and accurately your team turns incoming payments into applied cash. Running the diagnostic in this guide will tell you which problem you actually have before you spend budget on a fix that targets the wrong one.


Copyright 2023
